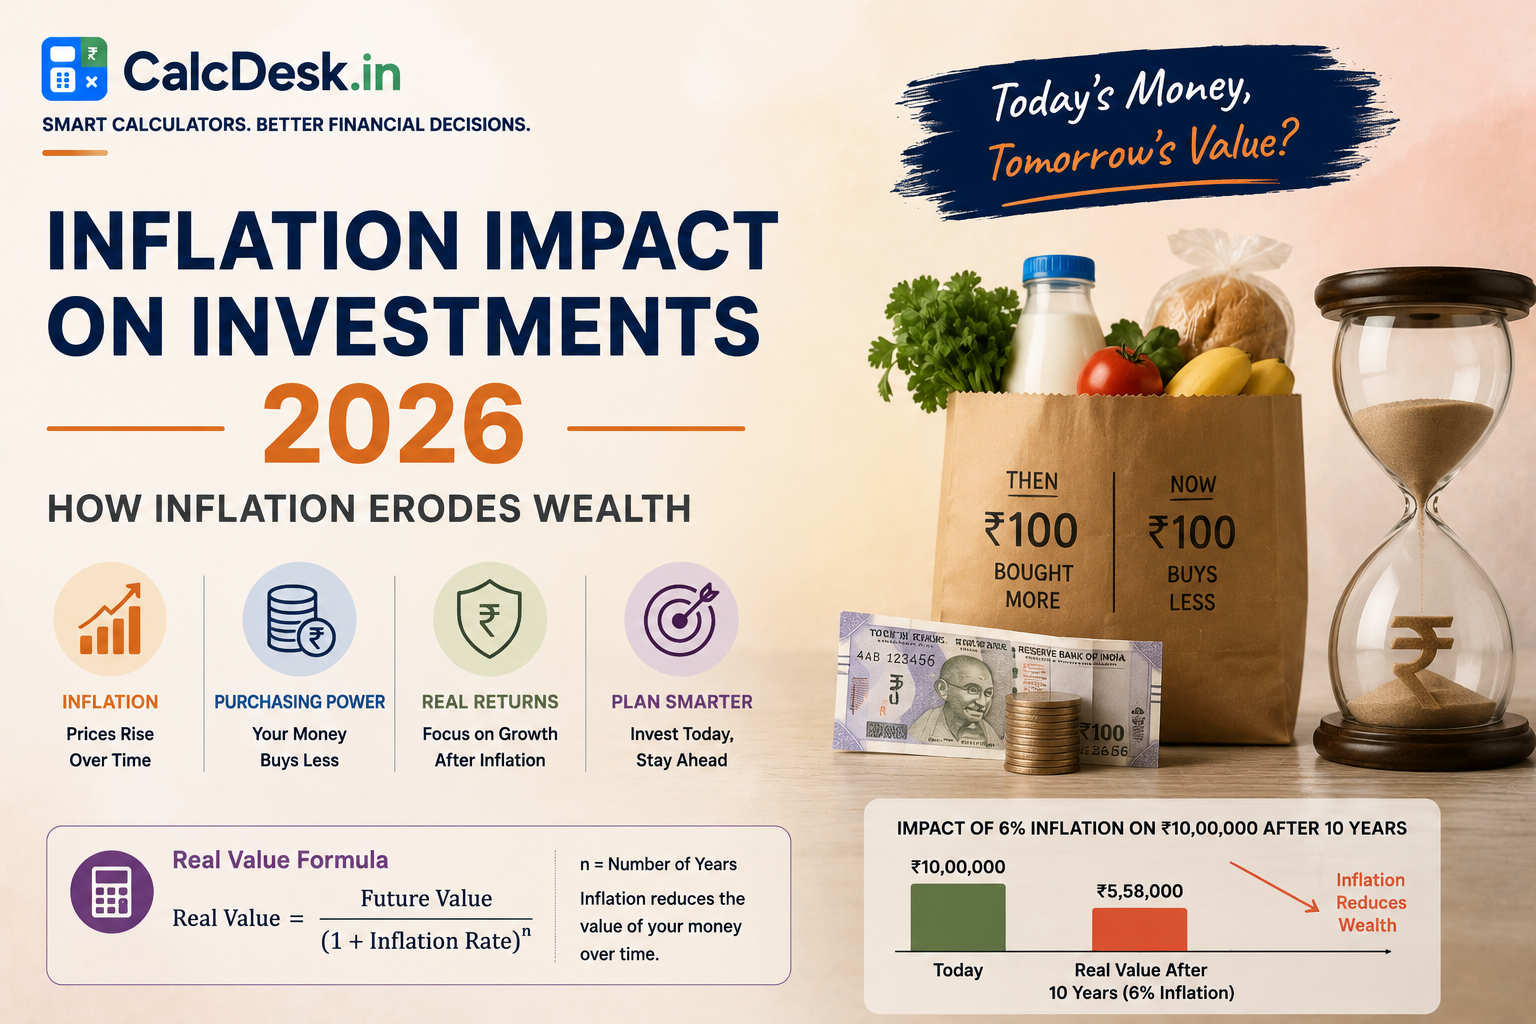
Inflation Impact on Investments 2026 — How Inflation Erodes Wealth
Inflation is the silent wealth destroyer that most Indian investors underestimate. At 5% annual inflation, ₹1 lakh today will have the purchasing power of just ₹61,391 after 10 years — a loss of nearly 39% in real value, even if the nominal amount stays the same. If your investments don’t consistently outpace inflation, you’re actually getting poorer over time, regardless of how much your account balance grows.
This guide explains how inflation works, the difference between nominal and real returns, which asset classes have historically beaten India’s inflation, and practical strategies to inflation-proof your portfolio. Use CalcDesk’s SIP Calculator to see how your investments perform against inflation over time.
What is Inflation — The Basics
Inflation is the rate at which the general price level of goods and services rises over time. In India, the RBI monitors two key inflation measures:
- CPI (Consumer Price Index): Measures retail price changes for a basket of goods and services consumed by households. This is the primary inflation target for RBI (target: 4% ±2%)
- WPI (Wholesale Price Index): Measures price changes at the producer/wholesale level, often a leading indicator of future CPI
India’s CPI inflation has averaged approximately 5-6% over the past decade, with food inflation frequently running higher. Even the RBI’s target of 4% means prices double every 18 years (using the Rule of 72).
The Purchasing Power Erosion — Numbers That Shock
| Today’s ₹1 Lakh Worth After… | At 4% Inflation | At 5% Inflation | At 6% Inflation |
|---|---|---|---|
| 5 years | ₹82,193 | ₹78,353 | ₹74,726 |
| 10 years | ₹67,556 | ₹61,391 | ₹55,839 |
| 15 years | ₹55,526 | ₹48,102 | ₹41,727 |
| 20 years | ₹45,639 | ₹37,689 | ₹31,180 |
| 30 years | ₹30,832 | ₹23,138 | ₹17,411 |
Nominal vs Real Returns — The Critical Distinction
Real Return Formula
Exact formula: Real Return = ((1 + Nominal) / (1 + Inflation)) − 1
Example: 12% nominal return, 5% inflation
Real Return = (1.12 / 1.05) − 1 = 6.67%
How Inflation Destroys FD Returns — A Worked Example
FD investor in 30% tax bracket, 7% FD rate, 5% inflation
Nominal FD return: 7%
Less income tax (30% slab): 7% × (1 − 0.30) = 4.9% post-tax nominal return
Less inflation (5%): Real post-tax return = 4.9% − 5% = −0.1%
Result: You’re losing purchasing power even with a “good” FD rate
At 20% tax slab: post-tax = 5.6%, real = 0.6% — barely positive
Conclusion: FDs are negative real returns for taxpayers in 30% bracket at current rates
How Inflation Affects Different Asset Classes
| Asset Class | 10-Year Nominal CAGR | Real Return (vs 5% inflation) | Verdict |
|---|---|---|---|
| Equity MF (Large Cap SIP) | 12-14% | 7-9% | ✅ Strong inflation beater |
| Gold | 10-12% | 5-7% | ✅ Good inflation hedge |
| Real Estate (metro) | 8-10% | 3-5% | ✅ Moderate inflation beater |
| PPF (tax-free) | 7.1% | ~2% (effective, tax-free) | ⚠️ Marginal positive real return |
| Bank FD (taxable, 30% slab) | 6.5-7% | −0.5% to 0% | ❌ Negative real return |
| Savings Account | 3-4% | −1% to −2% | ❌ Significant real loss |
Worked Example 1 — FD vs Equity SIP over 20 Years
₹10,000/month invested for 20 years — FD vs equity SIP
Total invested: ₹24,00,000
FD (7% nominal, 5% inflation):
Nominal corpus: ₹52.8L | Real corpus (in today’s ₹): ₹52.8L / (1.05)^20 = ₹19.9L in real terms
Real gain over invested amount: just ₹5.9L after 20 years in purchasing power terms
Equity SIP (12% nominal, 5% inflation):
Nominal corpus: ₹99.9L | Real corpus: ₹99.9L / (1.05)^20 = ₹37.7L in real terms
Real gain: ₹13.7L in purchasing power — more than 2× the FD investor’s real gain
Worked Example 2 — Retirement Planning with Inflation
How much do you need for retirement if expenses are ₹50,000/month today?
Current monthly expenses: ₹50,000
Years to retirement: 25 years
Inflation rate assumed: 5%
Monthly expenses at retirement: ₹50,000 × (1.05)^25 = ₹1,69,318/month
Corpus needed at retirement (to last 25 years at 6% post-retirement return): approximately ₹2.85 crore
Without inflation adjustment, many people plan for a ₹1 crore corpus that won’t sustain their actual retirement lifestyle
Inflation-Protection Investment Strategies
- Increase equity allocation for long-term goals: Equity is the single most effective long-term inflation beater available to Indian retail investors. A ₹5,000/month SIP in a diversified equity fund over 20 years creates a real corpus far exceeding FD alternatives
- Use PPF for guaranteed real returns: At 7.1% tax-free, PPF offers approximately 2% real return — positive and safe. Max out ₹1.5L/year as a low-risk inflation buffer
- Include gold in portfolio (5-10%): Gold has historically preserved purchasing power over decades. Invest via Sovereign Gold Bonds for additional 2.5% interest yield on top of gold price appreciation
- Avoid excess savings account/liquid funds for long-term: 3-4% savings account rates vs 5-6% inflation means real losses mount quickly over years
- Increase SIP amount annually: If your SIP stays flat while inflation rises, the real purchasing power of your investment decreases each year. Aim to increase SIP by at least 5-10% annually
⚠️ The retirement trap: Planning retirement based on today’s expenses without inflating them is the single biggest financial planning mistake. ₹50,000/month today becomes ₹1.69 lakh/month after 25 years at 5% inflation. Always calculate your retirement corpus target in future rupees, not today’s rupees.
💡 Practical rule: Your overall investment portfolio should earn at least 2-3% above inflation annually in real terms to grow your wealth meaningfully. For an FD-heavy investor in a high tax bracket, this is essentially impossible — equity allocation is non-negotiable for long-term investors seeking to build real wealth.
📈 Calculate Your Real Returns — Free
Project SIP growth in both nominal and inflation-adjusted terms to see real wealth creation.
→ Open SIP CalculatorIndia CPI Inflation History (2014–2026)
Understanding where India’s inflation has been is essential for calibrating long-term planning assumptions. The RBI operates under a flexible inflation targeting framework with a mandate to keep CPI at 4%, within a tolerance band of ±2% (i.e., 2–6%). Below is the actual CPI trajectory over the past decade:
| Financial Year | CPI Inflation | Key Driver |
|---|---|---|
| FY 2014-15 | 5.9% | Food and fuel prices elevated |
| FY 2015-16 | 4.9% | Gradual moderation, lower oil |
| FY 2016-17 | 4.5% | Demonetisation demand compression |
| FY 2017-18 | 3.6% | Below RBI target — rare occurrence |
| FY 2018-19 | 3.4% | Lowest in the decade |
| FY 2019-20 | 4.8% | Onion price spike, food inflation |
| FY 2020-21 | 6.2% | COVID supply disruption, above band |
| FY 2021-22 | 5.5% | Supply chain normalisation |
| FY 2022-23 | 6.7% | Russia-Ukraine commodity shock, fuel |
| FY 2023-24 | 5.4% | Moderating core, sporadic food spikes |
| FY 2024-25 | 4.8% (est.) | Easing commodity prices, RBI tightening impact |
RBI target: 4% with tolerance band ±2% (operative range: 2–6%). Food inflation has been structurally higher — in FY 2022-23, food inflation hit 7.8% while core (non-food, non-fuel) ran at approximately 6%. Core inflation is more sticky and matters more for monetary policy; food spikes are often considered transient. For long-term financial planning, 6% is the conservative assumption — it is above the RBI midpoint but reflects realistic average experience over a decade including the shock years.
The ₹1 Crore Problem — Inflation’s Impact on Retirement
The most damaging misconception in Indian retirement planning is treating ₹1 crore as an adequate retirement corpus without adjusting for inflation. Here is the arithmetic that exposes the gap:
Why ₹1 Crore Is Not Enough — The Inflation Math
Step 1 — Future value of today’s ₹1 Cr spending need at 6% inflation over 20 years:
₹1,00,00,000 × (1.06)^20 = ₹1,00,00,000 × 3.207 = ₹3.21 crore needed in 20 years
In other words, if you spend ₹1 Cr per year today, you’ll need ₹3.21 Cr per year in 20 years to maintain the same lifestyle.
Step 2 — SIP needed today to accumulate ₹3.21 Cr in 20 years at 12% CAGR:
Using SIP future value factor for 12% over 20 years (240 months): FV factor ≈ 989.26 per ₹1 SIP
Monthly SIP required = ₹3,21,00,000 ÷ 989.26 = ₹32,450/month
Step 3 — Monthly retirement corpus calculation:
Need ₹50,000/month in today’s money. In 20 years at 6% inflation: ₹50,000 × (1.06)^20 = ₹1,60,357/month
Annual income needed at retirement: ₹1,60,357 × 12 = ₹19.2 lakh/year
At a 7% withdrawal rate: Corpus needed = ₹19.2L ÷ 0.07 = ₹2.74 crore (in future rupees)
Key lesson: ₹1 crore in 20 years will not fund a ₹50,000/month retirement — ₹2.74 crore will. Planning based on today’s values without inflating is the most common and costly retirement planning error.
Inflation-Indexed Instruments in India — What Actually Exists
Most investors assume there are CPI-linked investment options in India similar to US TIPS (Treasury Inflation-Protected Securities). The reality is more limited, but viable alternatives exist:
RBI Floating Rate Savings Bond (2020): Rate = NSC rate + 0.35%; currently 8.05% per annum. Revised every 6 months (January and July). Available directly via RBI Retail Direct portal and major banks. Not directly CPI-linked, but floats with government savings rates which broadly track inflation trends. Tenure: 7 years. No premature withdrawal except for senior citizens (after 4–6 years depending on age). Safe, government-backed, but illiquid.
Sovereign Gold Bonds (SGB): Gold price has delivered approximately 10–12% CAGR over 20-year periods in India, broadly tracking and often exceeding long-term inflation. SGBs offer 2.5% per annum interest on top of gold price appreciation. On maturity (8 years), capital gains are fully tax-free. Best inflation hedge available in India for retail investors. SGB issues are periodic — check RBI calendar for subscription windows.
True TIPS equivalent: India does not currently offer a retail CPI-linked government bond. The Inflation Indexed National Savings Securities (IINSS-C) programme was discontinued. The government does issue CPI-linked bonds to institutional investors but these are not accessible to retail investors through standard channels.
Practical inflation-protection portfolio allocation: For a salaried investor with a 20+ year horizon, a balanced approach works: allocate one-third to equity funds (beats inflation over long periods through business earnings growth), one-third to real estate or REITs (rental income tracks inflation, capital appreciation beats it in quality locations), one-sixth to Sovereign Gold Bonds (CPI hedge plus interest), and one-sixth to floating-rate instruments like the RBI Floating Rate Bond or floating-rate debt funds. Avoid locking more than 20% of long-term wealth into fixed-rate FDs — their real post-tax return is negative in high-tax brackets at current rates.